Introduction
Canada’s housing market in 2026 remains one of the country’s most important economic and social issues, affecting homeowners, renters, first-time buyers, investors, and communities across the country. Mortgage rates, home prices, rental costs, housing supply, population growth, construction activity, and government policies are all shaping the housing landscape. However, conditions are not the same everywhere, with significant differences between provinces, cities, and property types.
For first-time buyers, understanding down payments, mortgage qualification, the FHSA, the Home Buyers’ Plan, closing costs, and affordability is increasingly important. Renters are also facing changing conditions as vacancy rates, rental supply, rent prices, tenant protections, and new housing construction continue to influence the rental market. At the same time, federal, provincial, and municipal governments are introducing policies and programs aimed at increasing housing supply and improving affordability.
This comprehensive guide to Canada Housing 2026 examines the major trends shaping the market, including home prices, sales and listings, housing supply and demand, mortgage rates, rental conditions, new developments, affordable housing policies, and Airbnb and short-term rental regulations. By looking at these issues across different regions and housing segments, readers can better understand how Canada’s housing market is changing and what factors are likely to remain important throughout 2026.
Market Updates
Canada Housing Market 2026
Canada’s housing market in 2026 is being shaped by mortgage rates, borrowing costs, home prices, sales activity, and changing buyer demand. Market conditions can differ significantly between provinces and cities. Some areas may see stronger demand while others experience slower sales. Housing supply also remains an important factor affecting affordability. Government housing policies and interest-rate decisions can further influence the market. Overall, buyers and sellers are watching prices, listings, and financing conditions closely
Canadian Home Prices
Canadian home prices can vary widely depending on the province, city, property type, and local supply. Changes in mortgage rates can affect how much buyers are able to spend on a home. When demand rises faster than available listings, prices can face upward pressure. When sales slow and inventory increases, sellers may have to adjust asking prices. Detached homes, condos, and townhouses can also follow different price trends. Tracking benchmark prices provides a clearer picture of broader housing conditions.
Housing Market by Province
Canada’s housing market does not move in the same direction across every province. Ontario and British Columbia have major high-priced markets, while provinces such as Alberta, Saskatchewan, and Manitoba often have different affordability conditions. Atlantic provinces can also experience distinct trends based on population growth and local employment. Differences in construction, migration, income, and available housing influence provincial markets. Comparing provinces helps explain why national housing figures may not reflect every region. Provincial data is therefore important for understanding local housing conditions.
Housing Market by Major City
Major Canadian cities can experience very different housing conditions even during the same period. Toronto, Vancouver, Calgary, Edmonton, Montréal, Ottawa, and other large markets have different prices, inventories, employment bases, and population trends. Some cities may experience stronger buyer demand while others see more balanced conditions. Condo and detached-home markets can also behave differently within the same city. Local construction activity is another important factor. City-level data gives buyers and sellers a more accurate view of their specific market.
Home Sales and Listings
Home sales and new listings are two important indicators of housing-market activity. Rising listings can give buyers more choices and may reduce competition between purchasers. Strong sales combined with limited listings can create tighter market conditions. If sales decline while inventory increases, homes may take longer to sell. The sales-to-new-listings ratio can also help indicate the balance between buyers and sellers. Monthly changes should be viewed alongside longer-term trends rather than on their own.
Housing Supply and Demand
Housing supply and demand play a major role in determining prices and market conditions. Strong population growth can increase demand for homes, especially in major employment centres. New construction can add supply, but building enough homes can take years. Land availability, construction costs, financing, and development rules can affect how quickly new housing reaches the market. When demand exceeds available supply, affordability can become more difficult. A better balance between supply and demand is an important part of Canada’s long-term housing challenge.
Condo Market
Canada’s condo market is influenced by affordability, interest rates, investor activity, construction levels, and demand from first-time buyers. Condos generally have lower purchase prices than many detached homes, making them an important option in expensive cities. However, condo owners also face monthly maintenance fees and other ownership costs. A large number of newly completed units can increase available inventory. Market conditions can therefore differ between new condos and resale properties. Local employment and population growth also influence condo demand.
Detached Home Market
Detached homes remain an important part of Canada’s housing market and are often in strong demand among families. Prices for detached properties can be significantly higher than condos because of larger living areas and land ownership. Limited land in major urban centres can place additional pressure on detached-home prices. Suburban and smaller-city markets may provide different affordability options. Mortgage rates also have a major effect on buyers’ purchasing power. Sales, listings, prices, and days on market help show how the detached segment is performing.
Housing Market Forecasts
Housing forecasts examine factors such as interest rates, economic growth, employment, population growth, construction, and household formation. Forecasts can differ because economists and housing organizations use different assumptions and models. A change in mortgage rates or economic conditions can also alter expectations quickly. National forecasts may not accurately describe individual provinces or cities. Buyers and sellers should therefore consider local market data alongside broader forecasts. Forecasts are estimates rather than guaranteed future outcomes.
Regional Housing Trends
Regional housing trends show how market conditions differ across Canada’s urban, suburban, and rural communities. Population growth, migration, employment opportunities, local industries, and housing construction can all influence regional demand. Some regions may experience rising listings while others face limited supply. Affordability can also vary considerably between neighbouring communities. Examining regional data helps identify differences that national statistics can hide. These trends are especially useful for understanding where housing activity is changing and why.
First-Time Buyers
First-Time Home Buyer Guide
Buying your first home in Canada involves several important steps, from checking your budget to getting mortgage pre-approval. First-time buyers should understand the down payment, mortgage, closing costs, and ongoing ownership expenses. It is also important to compare homes based on location, condition, and affordability. Government programs may provide additional support to eligible buyers. A clear buying plan can help reduce unexpected costs. Understanding the process before making an offer can make the purchase easier to manage.
First-Time Buyer Down Payment
The down payment is one of the biggest costs for a first-time home buyer in Canada. The minimum amount depends on the purchase price and applicable mortgage rules. Buyers who put down 20% or more may generally avoid mortgage default insurance. A larger down payment can also reduce the amount that needs to be borrowed. Buyers should make sure they still have enough money for closing costs and an emergency fund. Savings programs such as the FHSA may also help eligible buyers build their down payment.
First Home Savings Account (FHSA)
The First Home Savings Account, or FHSA, is designed to help eligible Canadians save for their first home. Contributions can provide a tax deduction, while qualifying withdrawals for a first home can generally be tax-free. The account has annual and lifetime contribution limits. Buyers should understand the eligibility requirements before opening or using an FHSA. The account can be particularly useful when combined with other home-buying programs. Rules and limits should always be checked against the latest government information.
Home Buyers’ Plan (HBP)
The Home Buyers’ Plan allows eligible individuals to withdraw money from their RRSP to help purchase or build a qualifying home. The withdrawal is subject to program rules and must generally be repaid to the RRSP over a specified period. It can provide access to existing retirement savings when buying a first home. Buyers should understand the repayment requirements before making a withdrawal. The HBP can also be considered alongside the FHSA where eligibility requirements are met. Government rules should be reviewed before using the program.
First-Time Buyer Tax Benefits
First-time home buyers may have access to federal or provincial tax-related benefits depending on their situation and where they purchase. These programs can reduce certain costs associated with buying a qualifying home. Eligibility may depend on factors such as previous home ownership, property type, and residency. Some benefits are claimed through a tax return, while others may involve rebates or credits. Buyers should keep records of eligible expenses and purchase documents. Tax rules can change, so current requirements should be confirmed before claiming a benefit.
Mortgage Pre-Approval
Mortgage pre-approval gives a first-time buyer an indication of how much they may be able to borrow before shopping for a home. Lenders typically review income, debts, credit history, employment, and available savings. Pre-approval can help buyers set a realistic price range and understand potential monthly payments. It does not always guarantee final mortgage approval because the property itself may also need to meet lender requirements. Buyers should compare interest rates and mortgage terms from different lenders. Keeping the budget below the maximum approved amount can also leave room for other homeownership costs.
Closing Costs
Closing costs are expenses that buyers must pay in addition to the purchase price of a home. They can include legal fees, land transfer taxes, appraisal fees, title insurance, inspections, and other transaction-related expenses. The exact amount varies depending on the property, province, municipality, and type of transaction. First-time buyers should include these costs when calculating how much cash they need. Some provinces and municipalities offer programs that may reduce certain costs for eligible buyers. Planning for closing costs early can help prevent a cash shortage at closing.
Home Inspection
A home inspection can help a first-time buyer understand the physical condition of a property before completing the purchase. An inspector may examine areas such as the roof, foundation, plumbing, electrical systems, heating, and visible structural components. The inspection can identify potential repairs or maintenance issues that may not be obvious during a viewing. Buyers should understand that an inspection does not guarantee that every hidden problem will be discovered. The inspection report can nevertheless provide useful information before making or finalizing a purchase. Buyers should also ask questions about any significant issues identified in the report.
Affordable Cities for First-Time Buyers
Affordability for first-time buyers varies significantly between Canadian cities and depends on home prices, incomes, mortgage rates, and local living costs. Cities in Alberta, Saskatchewan, Manitoba, and some smaller communities may offer different entry-level options than Canada’s most expensive housing markets. Edmonton, Calgary, Regina, Winnipeg, and other markets can have different combinations of prices and employment opportunities. Buyers should compare the full cost of ownership rather than looking only at the purchase price. Commute times, property taxes, neighbourhood services, and future housing supply can also matter. City-level housing data is useful when comparing potential locations.
Rental Crisis
Canada Rental Market
Canada’s rental market is influenced by rent prices, vacancy rates, population growth, and the availability of rental homes. Demand can be particularly strong in major cities where employment and population growth attract more residents. Rental conditions can vary significantly between provinces and communities. New apartment construction is adding supply in some markets, while other areas continue to face limited availability. Interest rates and home prices can also affect rental demand when buying becomes less affordable. Monitoring rents and vacancy rates helps show how the rental market is changing.
Rental Vacancy Rates
The rental vacancy rate measures the share of rental homes that are available for tenants to rent. A low vacancy rate generally means fewer available units and can indicate stronger competition among renters. A higher vacancy rate can give tenants more choices and may reduce pressure on landlords to increase asking rents. Vacancy rates can differ substantially between provinces, cities, and neighbourhoods. New apartment construction can gradually increase the number of available rental homes. Tracking vacancy rates alongside rent prices helps explain changes in local rental conditions.
Affordable Rental Housing
Affordable rental housing is a major issue for households that spend a large portion of their income on housing. The challenge can be particularly significant in cities where rents have increased faster than household incomes. Affordable housing can include subsidized units, below-market rentals, and purpose-built rental homes. Government programs and non-profit housing providers can help increase access for eligible households. Building more rental housing can also improve long-term availability. Affordability depends not only on rent but also on income, utilities, transportation, and other living expenses.
Housing Shortage
Canada’s housing shortage affects both renters and people trying to purchase homes. When the number of households seeking housing grows faster than new homes are built, competition for available properties can increase. Rental housing can be especially affected in rapidly growing cities. Construction costs, land availability, financing conditions, and development rules can influence how quickly new homes are added. Governments are introducing different measures to encourage housing construction and improve supply. The scale of the shortage can vary considerably between regions.
Rental Supply
Rental supply refers to the number of homes available for people who rent rather than own. Purpose-built rental apartments are an important part of this supply, alongside condominiums and other privately rented properties. New construction can increase supply, but projects can take several years from planning to completion. Higher financing and construction costs can affect the number of new rental projects. Population growth can also increase demand faster than supply in some communities. Increasing rental supply is therefore an important part of addressing affordability and vacancy pressures.
Tenant Rights
Tenant rights in Canada are mainly governed by provincial and territorial laws, so the rules can differ depending on where a rental property is located. These laws generally address areas such as leases, rent increases, repairs, privacy, deposits, and eviction procedures. Tenants should understand the terms of their rental agreement and keep records of important communications. Landlords also have legal responsibilities toward their tenants. Disputes may be handled through a provincial or territorial residential tenancy authority or tribunal. Tenants should check the rules that apply specifically to their province or territory.
Rent Control
Rent control refers to legal limits or rules governing how and when landlords can increase rent. Canada does not have one nationwide rent-control system, because provinces and territories establish their own rental rules. Some jurisdictions limit annual increases for certain rental units, while exemptions may apply to particular properties or situations. Rules can also differ for existing tenants and newly rented units. Tenants should check the applicable provincial or territorial regulations before assuming a specific limit applies. Understanding local rent-control rules is especially important when renewing a lease or receiving a rent-increase notice.
Rental Assistance Programs
Rental assistance programs can help eligible households manage housing costs when their income is limited or rent is difficult to afford. Support may come through federal, provincial, territorial, or municipal programs, depending on the applicant’s location and circumstances. Assistance can include housing benefits, rent supplements, subsidized housing, or other forms of financial support. Eligibility may depend on income, household size, age, disability, or other requirements. Programs and application processes vary across Canada. Renters should check current government programs available in their province or municipality.
Rental Market by Province and City
Rental conditions can look very different across Canadian provinces and cities because population growth, employment, construction, and housing costs vary by region. Toronto and Vancouver have historically faced high rental costs, while cities such as Edmonton, Calgary, Winnipeg, and Regina can have different affordability and vacancy conditions. Even within one province, rental prices can vary significantly between major cities and smaller communities. New construction can also change local vacancy and rent trends over time. Comparing rents, vacancy rates, and rental supply by city provides a more useful picture than a single national figure.
Mortgage & Rates
Mortgage Rates in Canada
Mortgage rates determine the interest borrowers pay on their home loans and can have a major effect on monthly payments. Canadian mortgage rates vary between lenders and depend on factors such as the mortgage type, term, credit profile, and market conditions. Fixed rates provide a set interest rate for the agreed term, while variable rates can change over time. Government and central-bank decisions can indirectly influence borrowing costs. Buyers should compare both the interest rate and the full mortgage terms before choosing a lender.
Bank of Canada Rate Changes
The Bank of Canada’s policy interest rate influences borrowing conditions across the Canadian economy. Changes in the policy rate can affect variable mortgage rates and other borrowing costs. Fixed mortgage rates are influenced more directly by bond-market conditions and lender pricing. When rates change, homeowners with variable mortgages may see their payments or interest costs change. The effect on fixed-rate borrowers is usually more noticeable when they renew their mortgages. Understanding these differences helps homeowners assess how rate changes may affect their finances.
Fixed vs Variable Mortgages
A fixed-rate mortgage keeps the interest rate unchanged for the length of the mortgage term. This can make payments easier to plan because the rate does not normally change during that term. A variable-rate mortgage has an interest rate that can change according to the lender’s pricing and underlying market conditions. Variable mortgages may offer different payment and interest-rate structures depending on the lender. Each option carries different exposure to future interest-rate changes. Borrowers should compare payment stability, flexibility, penalties, and total borrowing costs.
Mortgage Qualification
Mortgage qualification involves a lender assessing whether a borrower can reasonably manage the proposed mortgage. Lenders may consider income, employment, credit history, existing debts, down payment, and other financial information. Borrowers generally need to provide documents such as proof of income, identification, bank statements, and information about their debts. The lender also evaluates the property being purchased. Qualification does not simply depend on how much a buyer wants to borrow. A realistic budget should consider mortgage payments as well as taxes, insurance, utilities, maintenance, and other household expenses.
Mortgage Stress Test
Canada’s mortgage stress test is used to assess whether borrowers could continue making mortgage payments if interest rates were higher. It applies to many federally regulated mortgage borrowers, although specific rules and exemptions can vary. The qualifying rate is higher than the actual mortgage rate used by the borrower. This means someone may qualify for a smaller mortgage than their preferred monthly budget might initially suggest. The test is intended to provide a measure of financial resilience. Borrowers should check the current qualifying-rate rules when applying or renewing.
Mortgage Renewal
A mortgage renewal happens when the existing mortgage term ends and the borrower continues financing the remaining balance. The lender typically provides renewal information before the maturity date. Homeowners do not necessarily have to accept the renewal offer from their existing lender. They can compare rates and terms from other lenders before renewing. Borrowers should also review whether their financial situation or mortgage needs have changed. Comparing options before the renewal deadline can help ensure the new mortgage matches their current circumstances.
Mortgage Refinancing
Mortgage refinancing involves changing the existing mortgage arrangement, often to access home equity, consolidate debt, or obtain different terms. Refinancing can increase the amount borrowed against the property and may involve appraisal, legal, or other costs. Breaking an existing mortgage before the end of its term can also result in a prepayment penalty. Borrowers should calculate the total cost rather than looking only at a lower interest rate. Refinancing can affect the mortgage amortization period and future interest costs. Professional financial or mortgage advice may be useful for more complex situations.
Down Payment Requirements
The down payment is the portion of the home purchase price that a buyer pays without borrowing through a mortgage. Canadian minimum down-payment requirements depend on the purchase price and applicable federal mortgage rules. Buyers who make a down payment of less than 20% generally need mortgage loan insurance when the mortgage is eligible for such insurance. A larger down payment reduces the amount that needs to be financed. Buyers should also keep funds available for closing costs and unexpected expenses. Savings programs such as the FHSA and HBP may provide additional options for eligible first-time buyers.
Mortgage Affordability
Mortgage affordability depends on more than the price of a home. Buyers need to consider their income, debts, down payment, interest rate, property taxes, heating costs, insurance, and other regular expenses. Higher mortgage rates can reduce the amount a household can comfortably borrow. A lender’s maximum approval amount should not automatically be treated as a household’s ideal budget. Buyers should also consider future changes in income, expenses, and interest rates. Building an affordable budget before house hunting can help reduce financial pressure after purchase.
First-Time Buyer Mortgages
First-time buyers may have access to mortgage options and government programs designed to help with the cost of purchasing a home. The mortgage process still involves qualification requirements, a down payment, affordability assessment, and applicable mortgage rules. Buyers should compare lenders, interest rates, mortgage terms, and prepayment options. Programs such as the FHSA and HBP may also help eligible buyers with their purchase. First-time buyers should budget for closing costs in addition to the down payment. Understanding the complete cost of homeownership is important before committing to a mortgage.
New Developments
New Housing Projects in Canada
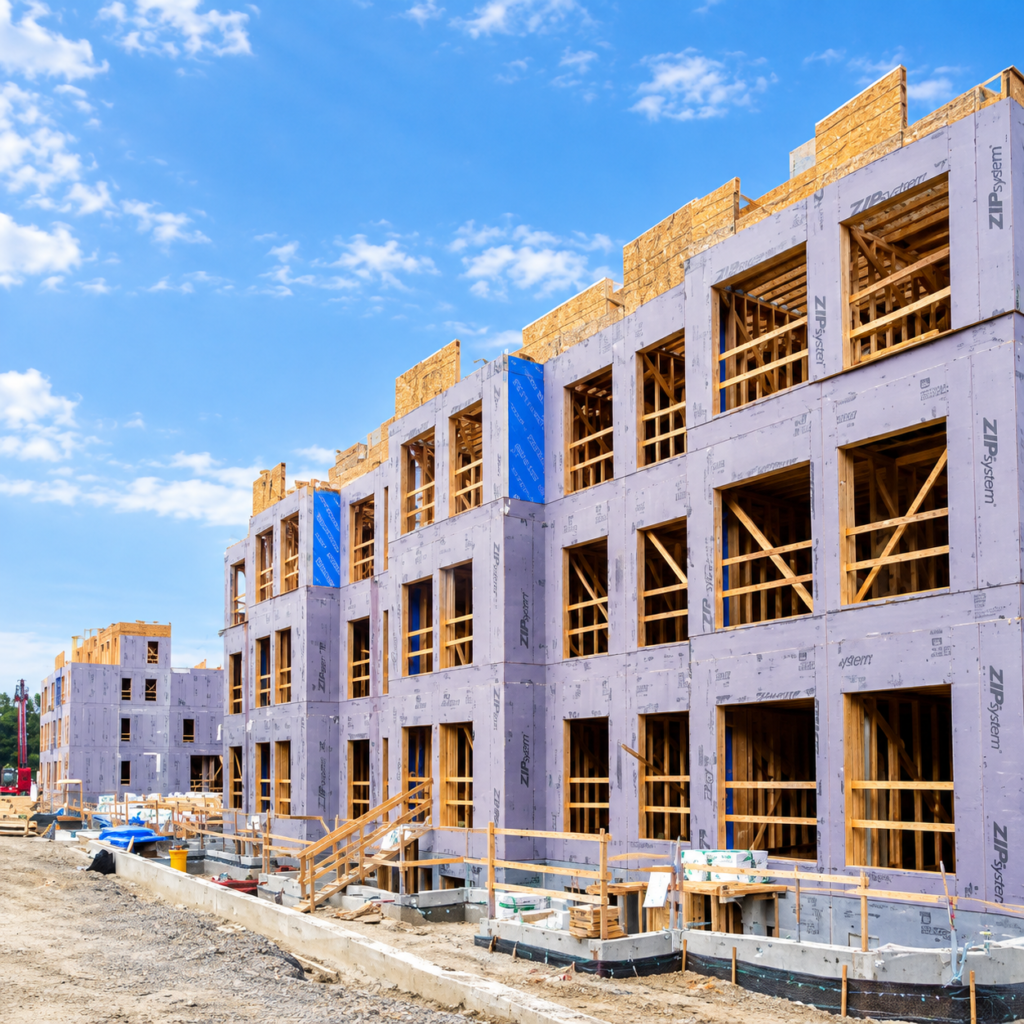
New housing projects are being developed across Canada to increase the supply of homes for a growing population. Projects include detached houses, townhomes, condos, rental apartments, and mixed-use communities. Construction activity can vary significantly between provinces and cities because of land costs, financing, demand, and local planning rules. Government housing initiatives are also supporting some new construction and development. Large projects can take several years to move from planning to completion. Tracking new housing starts and construction activity helps show how Canada’s housing supply is expanding.
New Condos and Apartments
New condos and purpose-built rental apartments are an important part of Canada’s urban housing development. Developers are building new units in areas where population growth and housing demand remain strong. Condo projects are often concentrated near transit, employment centres, and established neighbourhoods. New rental apartments can increase the supply available to tenants and potentially improve vacancy conditions over time. Construction costs and financing conditions can influence how many projects move forward. Buyers and renters should also consider completion dates, maintenance costs, and the location of new developments.
Major Residential Developments
Major residential developments can add thousands of homes through large master-planned communities and multi-building projects. These developments may include houses, apartments, condos, retail space, parks, schools, and community facilities. Their scale means construction can take several years and may occur in multiple phases. Transportation and other infrastructure often need to expand alongside the new housing. Population growth and local housing demand can influence where major projects are planned. Monitoring major developments provides insight into the future housing supply of Canadian communities.
Affordable Housing Projects
Affordable housing projects are designed to provide homes at rents or prices that are more accessible to households with lower or moderate incomes. Projects can be developed by governments, non-profit organizations, housing providers, or private developers working with public programs. Some developments provide below-market rental units, while others focus on supportive or community housing. Funding, land availability, construction costs, and project approvals can affect delivery timelines. New affordable housing can help increase the supply available to households facing high housing costs. Programs and eligibility requirements vary depending on the project and jurisdiction.
New Homes by Province
New home construction varies across Canadian provinces because population growth, housing demand, land availability, and economic conditions differ. Ontario and British Columbia have large development markets, while Alberta has experienced significant residential growth in several communities. Saskatchewan, Manitoba, and Atlantic provinces also have new housing projects responding to local demand. Housing starts and building permits provide useful indicators of construction activity. Different provinces may also have different incentives and development policies. Comparing provincial construction data helps show where new housing supply is being added.
New Developments in Toronto
Toronto continues to see residential development through condos, rental buildings, townhomes, and large mixed-use communities. Many projects are concentrated around major transit routes and areas undergoing redevelopment. High land and construction costs can affect the price and type of new housing being built. Large projects may be delivered in multiple phases over several years. Rental housing is also an important part of Toronto’s future housing supply. Buyers and investors should check the latest project status, approvals, completion timelines, and local planning information.
New Developments in Vancouver
Vancouver’s housing development includes high-rise condos, purpose-built rental buildings, townhomes, and larger mixed-use communities. Limited land, high development costs, and strong housing demand have shaped the city’s development patterns. New projects are often planned around transit corridors and established urban centres. Government housing policies are also influencing the type and amount of new construction. Projects can take considerable time because of planning, approvals, financing, and construction stages. New developments are therefore an important part of understanding Vancouver’s future housing supply.
New Developments in Calgary
Calgary has experienced residential growth through new suburban communities, townhomes, apartments, and mixed-use developments. Population growth and relatively strong housing demand have supported construction in several parts of the metropolitan area. New communities often include roads, schools, parks, and other infrastructure as development expands. Apartment and rental construction has also become an important part of the city’s housing supply. Development activity can vary depending on construction costs, financing, and market conditions. New projects can provide additional housing options as Calgary continues to grow.
New Developments in Edmonton
Edmonton’s new housing development includes detached homes, townhomes, apartments, condos, and large planned communities. The city’s comparatively lower housing costs have supported demand from households looking for different affordability options. New developments are expanding in suburban areas while infill projects are adding housing within established neighbourhoods. Infrastructure such as roads, transit, utilities, schools, and recreational facilities can play an important role in supporting growth. Rental and multi-family construction is also contributing to the city’s housing supply. Development trends can change as population growth and market conditions evolve.
Infrastructure and Housing Growth
Housing growth depends heavily on infrastructure such as roads, public transit, water systems, electricity, schools, healthcare facilities, and community services. Large numbers of new homes can place additional pressure on existing infrastructure if services do not expand at the same pace. Governments and municipalities therefore often plan infrastructure alongside major residential developments. Transit investments can also encourage higher-density housing around stations and major corridors. Coordinated infrastructure development can support the expansion of new communities. Understanding both housing construction and infrastructure plans provides a broader picture of Canada’s urban growth.
Affordable Housing Policy
Federal Housing Policies
Canada’s federal housing policy focuses on increasing housing supply, improving affordability, supporting renters, and expanding affordable and community housing. In 2026, federal priorities include increasing construction, working with provinces and municipalities, and using public lands and financing tools to support new homes. Build Canada Homes is also being developed to help deliver large-scale affordable housing. The federal government is also working on the renewal of the National Housing Strategy.
Affordable Housing Programs
Canada has several programs supporting affordable housing construction, repairs, rental assistance, and community housing. The National Housing Strategy includes programs such as the Affordable Housing Fund, Apartment Construction Loan Program, and Co-operative Housing Development Program. These programs can support new construction as well as the repair and preservation of existing housing. Eligibility and funding arrangements vary by program and project. Federal, provincial, territorial, municipal, and non-profit organizations can play different roles in delivering housing projects.
Canada Housing Infrastructure
Housing development depends on infrastructure such as drinking-water systems, wastewater, stormwater management, and solid-waste services. The Canada Housing Infrastructure Fund provides up to $6 billion to support infrastructure that enables communities to build more homes. Funding can support both new infrastructure and upgrades to existing systems. Provinces, territories, municipalities, and Indigenous communities can participate through different funding streams. Infrastructure investment is therefore closely connected to the ability of communities to accommodate new housing growth.
Social Housing
Social housing provides homes intended to remain affordable for households that may have difficulty paying market rents. It includes housing operated by non-profit organizations, co-operatives, governments, and other community housing providers. Federal programs support both new affordable housing and the preservation of existing community housing. The National Housing Strategy also includes funding arrangements designed to protect existing social and community housing. Maintaining these homes is important because replacing affordable units can be difficult and costly.
Public Housing
Public housing generally refers to housing supported or operated by government or public housing organizations for eligible households. It can provide lower-cost housing to people who meet specific income or household requirements. Availability and application rules differ across provinces, territories, and municipalities. Federal housing programs can provide funding or support that works alongside provincial and territorial housing systems. In 2026, federal initiatives are also supporting public, affordable, and supportive housing developments in different communities.
Housing Supply Policies
Housing supply policies aim to make it easier and faster to build more homes where they are needed. Measures can include reducing development barriers, supporting infrastructure, increasing financing for construction, and making better use of public land. The federal government has also introduced funding intended to help provinces and territories implement measures that increase housing supply. Local zoning and approval processes remain important because municipalities have major responsibilities for land-use planning. The overall approach combines federal funding with provincial, territorial, and municipal actions.
First-Time Buyer Incentives
First-time buyers can access several federal measures intended to reduce the financial barriers to homeownership. These can include savings and tax-related programs such as the First Home Savings Account and the Home Buyers’ Plan. Some housing-related tax measures can also reduce costs for eligible buyers of qualifying homes. Eligibility requirements and program limits vary, so buyers need to check the rules that apply to their circumstances. First-time buyer measures are generally designed to work alongside, rather than replace, normal mortgage qualification requirements.
Rental Housing Programs
Federal rental housing programs support the construction, preservation, and affordability of rental homes across Canada. The Apartment Construction Loan Program provides financing intended to encourage the development of rental housing, while other National Housing Strategy programs support affordable and community housing. Rental assistance can also help eligible households manage housing costs. Program structures can involve federal, provincial, territorial, municipal, and non-profit partners. The availability of assistance depends on the program, location, household circumstances, and available funding.
Provincial Housing Policies
Provincial housing policies are important because provinces have major responsibilities for housing legislation, planning frameworks, rental rules, and relationships with municipalities. Each province can take a different approach to housing supply, affordability, rent regulation, development approvals, and homeownership support. Provincial programs can also work alongside federal funding to finance housing and infrastructure projects. Local governments then implement many policies through zoning, permits, and development planning. As a result, housing conditions and government support can differ substantially from one province and city to another.
Airbnb & Short-Term Rentals
Airbnb Rules in Canada
Airbnb and other short-term rentals are regulated mainly through provincial and municipal rules rather than one nationwide Airbnb law. Hosts may need to meet local zoning, registration, licensing, safety, and principal-residence requirements. Rules can be very different between cities, even within the same province. Federal tax rules also apply to income earned from short-term accommodation. Since 2024, income-tax deductions can be denied for non-compliant short-term rentals.
Short-Term Rental Regulations
Short-term rental regulations can cover where a property may operate, how many nights it can be rented, and whether the host needs a licence or registration. Some municipalities require the property to be the host’s principal residence. Other rules can involve landlord or condo-board approval, safety standards, insurance, and record keeping. Cities may also monitor online listings and impose penalties for violations. Hosts should check the rules of the municipality where the property is located before listing it.
Airbnb Rules by Province
Airbnb rules differ across Canada because provinces and municipalities have different housing, tenancy, tax, and licensing frameworks. Some provinces have introduced province-wide requirements, while municipalities may impose additional restrictions. A city can therefore have stricter requirements than another city in the same province. Hosts may need both provincial registration and local authorization in some locations. Checking both levels of government is important before starting a short-term rental business.
Toronto Airbnb Rules
Toronto allows short-term rentals only in a host’s principal residence, and operators must register with the City. The rules apply to rentals of less than 28 consecutive days. Hosts can register for either an entire-unit or partial-unit operation, with specific restrictions applying to partial-unit rentals. Registration must also be renewed annually. Toronto also applies a Municipal Accommodation Tax to short-term accommodation; the rate became 6% for stays beginning August 1, 2026.
Calgary Airbnb Rules
Calgary regulates short-term rentals through municipal licensing and local rules governing residential accommodation businesses. Hosts may need to obtain the appropriate business licence and meet applicable safety and property requirements. The exact requirements can depend on the type of property and how it is being operated. Condo rules, landlord agreements, and insurance requirements may also affect whether a unit can legally be used. Hosts should verify the current City of Calgary requirements before listing a property.
Short-Term Rental Taxes
Income earned from Airbnb and other accommodation-sharing platforms is generally taxable in Canada. The CRA may treat the income as rental income or business income depending on the services provided to guests. Short-term accommodation can also be subject to GST/HST, with registration generally required once taxable accommodation revenue exceeds the applicable $30,000 threshold over four calendar quarters. Municipal accommodation taxes may apply separately in some cities. Hosts should maintain records of rental income and eligible expenses.
Short-Term Rental vs Long-Term Rental
Short-term rentals generally involve stays for a limited period, while long-term rentals are designed for longer-term occupancy under residential tenancy arrangements. Short-term rentals can provide hosts with more flexibility and potentially different income patterns, but they usually involve greater regulatory and operating requirements. Long-term rentals provide more stable occupancy but are governed by provincial or territorial tenancy laws. Tax treatment can also differ depending on the rental arrangement and services provided. The better option depends on the property, local rules, costs, and the owner’s objectives
New Airbnb Regulations in Canada
Canada has introduced measures aimed at addressing short-term rentals that operate outside local rules or remove homes from the long-term rental market. Since 2024, federal tax rules generally deny deductions related to non-compliant short-term rentals after 2023. The federal government has also established the Short-Term Rental Enforcement Fund, providing $45.9 million over three years to support enforcement of local restrictions. Municipalities continue to introduce or update licensing, principal-residence, and enforcement rules. As a result, Airbnb hosts need to monitor both federal tax requirements and changing local regulations.
Final Verdict
Canada’s housing market in 2026 is being shaped by a combination of borrowing costs, housing supply, population growth, construction activity, rental demand, and government policy. There is no single housing trend that accurately describes every Canadian community. Market conditions can vary considerably between provinces, cities, neighbourhoods, and property types, making local data particularly important for understanding affordability and housing availability.
For buyers, mortgage qualification, down-payment requirements, closing costs, interest rates, and ongoing ownership expenses remain important considerations. First-time buyers can also explore programs such as the FHSA and Home Buyers’ Plan where eligible. Renters, meanwhile, need to pay attention to local vacancy rates, rental supply, tenant rights, rent-control rules, and available assistance programs.
Looking ahead, increasing housing supply will remain closely connected to infrastructure, construction capacity, financing, development approvals, and population growth. Federal and provincial policies can influence the pace of new construction, while municipalities play an important role through zoning, permitting, and local planning. Short-term rental regulations are another factor affecting housing availability and property use in many communities.
Overall, understanding Canada Housing 2026 requires looking beyond national averages. Home prices, rents, mortgage conditions, supply, and affordability can tell very different stories from one region to another. Keeping track of reliable market data, government programs, local regulations, and changing economic conditions provides a stronger foundation for understanding Canada’s housing landscape.
Table of Contents
Leave a Reply