Canada Housing & Real Estate
Introduction
Canada’s housing market remains a major concern for homebuyers, renters, property investors, and policymakers. Home prices, mortgage costs, rental availability, new construction, and government housing programs all influence whether Canadians can find suitable and affordable homes. Conditions vary significantly between cities and provinces, with markets such as Toronto and Vancouver facing different affordability pressures from Edmonton, Calgary, and other Canadian communities.
In 2026, key housing issues include changing buyer demand, the cost of borrowing, shortages of affordable rental homes, construction delays, and regulations governing short-term rentals such as Airbnb. This guide explores seven important areas of Canada’s housing and real estate market, explaining current trends, available programs, and the rules that buyers, renters, homeowners, and property investors should understand.
Market Updates
What are the latest developments in Canada’s housing market?
Canada’s housing market has shown uneven activity, with sales, prices, and inventory varying across regions. According to the Canadian Real Estate Association (CREA), national home sales fell 0.7% month over month in August 2026, while activity remained relatively stable compared with previous months. In September, national sales were 7.7% below the same month in 2025, indicating that demand remained under pressure.
How are home prices changing across Canadian cities and provinces?
Prices are moving differently depending on local supply, demand, and economic conditions. CREA’s Ontario data showed a benchmark home price of C$736,300 in September 2026, down 3.9% year over year. Some markets have experienced price declines as buyers become more cautious, while areas with stronger local demand or limited supply may remain comparatively resilient.
Which Canadian cities offer relatively affordable housing options?
Cities such as Edmonton, Regina, Saskatoon, Winnipeg, and some smaller communities generally offer lower home prices than Toronto and Vancouver. However, affordability depends on more than the purchase price: local wages, property taxes, insurance, transportation, utilities, and available employment all matter. Buyers should compare the total monthly cost of ownership rather than choosing a city solely because its homes appear cheaper.
How are home sales, housing inventory and buyer demand changing across Canada?
Sales have remained subdued in several markets, while elevated listings in some regions have given buyers more choice. In Ontario, active listings at the end of September 2026 were 17.8% above the five-year average and 39.8% above the 10-year average for that month. This greater inventory can improve negotiating power, although conditions differ between cities and property types.
What factors are influencing housing supply and demand in Canada?
Housing supply is influenced by construction costs, available land, zoning rules, infrastructure capacity, labour availability, financing, and the time needed to approve and build homes. Demand is affected by population growth, immigration, household formation, employment, incomes, mortgage rates, and buyer confidence. When housing construction fails to keep pace with demand in a particular area, affordability pressures can persist.
How do housing market trends in Toronto and Vancouver compare with those in Edmonton and Calgary?
Toronto and Vancouver have generally faced higher home prices and significant affordability challenges. Edmonton and Calgary have often offered lower purchase prices, although their markets are also influenced by local employment, migration, energy-sector conditions, and new construction. Rental markets differ too: in August 2026, average asking rent for apartments and condos was C$2,570 in Toronto and C$2,704 in Vancouver, compared with C$1,520 in Edmonton and C$1,825 in Calgary.
How are economic conditions and interest rates affecting Canada’s real estate market?
Interest rates influence the size of mortgage payments and the amount buyers can borrow. Employment trends, wage growth, inflation, consumer confidence, and lending requirements also affect purchasing decisions. When borrowing becomes more expensive or job security weakens, some buyers delay purchases; when financing becomes more affordable, demand may recover, depending on prices and the supply of available homes.
What major trends could shape Canada’s housing market in the coming years?
Key trends include the pace of new construction, rental supply, mortgage renewals, population growth, infrastructure investment, and policies designed to make homes more affordable. Modular construction, secondary suites, and higher-density housing could help expand supply if supported by suitable infrastructure and approvals. Future outcomes will depend on how these changes interact with borrowing costs, household incomes, and regional demand.
First-Time Buyers
What should first-time homebuyers know before purchasing a property in Canada?
First-time buyers should establish a realistic budget, review their credit history, compare mortgage offers, and obtain mortgage pre-approval before shopping. They should also consider property inspections, legal fees, insurance, property taxes, closing costs, and potential maintenance expenses. A home that fits the mortgage lender’s maximum approval may still be unaffordable once everyday expenses and emergency savings are included.
How much of a down payment is required to buy a home in Canada?
For an eligible home purchase below C$1.5 million using an insured mortgage, the minimum down payment is generally 5% on the first C$500,000 and 10% on the portion above C$500,000. A down payment of 20% or more generally avoids the requirement for mortgage default insurance, subject to applicable lending rules. Buyers should confirm eligibility and requirements with their lender.
How can the First Home Savings Account (FHSA) help Canadians save for their first home?
The FHSA allows eligible first-time homebuyers to save for a qualifying home with tax advantages. Contributions are generally tax-deductible, and qualifying withdrawals used to buy a home are tax-free. The annual contribution limit is C$8,000, with a lifetime limit of C$40,000. The account must be opened to begin accumulating FHSA participation room, so planning ahead can be useful.
How does the Home Buyers’ Plan (HBP) help eligible homebuyers use their RRSP savings?
The federal Home Buyers’ Plan allows eligible individuals to withdraw up to C$60,000 from their Registered Retirement Savings Plans (RRSPs) to buy or build a qualifying home. Withdrawals must meet the program’s conditions and generally need to be repaid to the RRSP over time. Eligible buyers may use both the HBP and an FHSA for the same home if they satisfy the rules for each program.
What federal and provincial programs support first-time homebuyers in Canada?
Federal support includes the FHSA, the Home Buyers’ Plan, and the Home Buyers’ Amount for eligible purchasers. Eligible buyers may also benefit from applicable GST/HST new-housing rebates and provincial or municipal programs, depending on the property and their circumstances. Program eligibility, tax treatment, and application deadlines can differ, so buyers should verify the current requirements with the Canada Revenue Agency and their provincial government.
How much income do buyers need to qualify for a mortgage in Canada?
There is no single income requirement because qualification depends on the home price, down payment, mortgage rate, property taxes, heating costs, other debts, and lender criteria. Lenders assess whether borrowers can afford payments using debt-service calculations and the mortgage stress test where applicable. A buyer with a larger down payment and fewer debts may qualify with less income than someone purchasing a more expensive home.
What additional costs should first-time homebuyers consider when purchasing a property?
Additional expenses may include land-transfer taxes, legal fees, a home inspection, title insurance, appraisal charges, mortgage default insurance, property insurance, and moving costs. Buyers may also need to budget for adjustments on property taxes or utilities, condo fees, repairs, and immediate maintenance. These expenses can add substantially to the cash required at closing, so they should be included in the purchase budget.
What are the biggest challenges facing first-time homebuyers in Canada?
High property prices, the difficulty of saving a down payment, mortgage qualification rules, and competition for suitable homes are major barriers. Rent and other living expenses can make it harder to save while buyers are also trying to manage debt. First-time buyers can improve their position by comparing different neighbourhoods, reviewing assistance programs, maintaining a strong financial record, and avoiding purchases that stretch their budget too far.
Rental Crisis
What are the latest developments in Canada’s rental housing market?
Canada’s rental market showed signs of easing in the asking prices for available homes in August 2026. Rentals.ca reported a national average asking rent of C$2,035 across property types, down 4.8% year over year and marking the 23rd consecutive month of annual decline. However, affordability remains difficult for many households, and rents vary substantially by location and unit size.
Why are rental prices rising in many Canadian cities?
Rents can rise when demand for housing exceeds the number of available units, particularly in cities with strong employment opportunities and limited affordable supply. Construction costs, population changes, local vacancy rates, and the mix of available apartments also influence asking rents. Although asking rents declined nationally year over year in the August 2026 report, some cities and unit types continued to experience increases.
Which Canadian cities have the highest average rents?
In August 2026, average asking rent for apartments and condos was C$2,704 in Vancouver, C$2,570 in Toronto, C$2,168 in Ottawa, C$1,955 in Montréal, C$1,825 in Calgary, and C$1,520 in Edmonton. Outside the six largest markets, North Vancouver recorded an average asking rent of C$3,018 across apartments and condos. These figures reflect asking rents for available listings, not the average paid by every existing tenant.
ow is the shortage of affordable rental housing affecting Canadians?
A shortage of affordable rental homes can force households to spend a larger share of income on housing, live in smaller spaces, share accommodation, or move farther from work and school. Some renters may postpone major life decisions or struggle to cover food, transportation, and other essential expenses. Low-income households and people who need accessible or supportive housing can face especially limited choices.
What factors are contributing to Canada’s rental housing crisis?
Factors include insufficient affordable housing in some markets, high construction and financing costs, limited serviced land, planning delays, and competition for homes in areas with strong demand. The availability of rental housing also depends on the type and location of units being built. More supply can ease pressure over time, but affordability also depends on household incomes, social housing, and targeted support for renters.
How are high rents affecting newcomers, students and low-income households?
Newcomers may face rental barriers because they have limited Canadian credit history, unfamiliarity with local rules, or difficulty finding housing before arriving. Students may compete for rooms near campuses, while low-income households can struggle to cover rent and other basic expenses. Access to reliable housing supports employment, education, settlement, and overall well-being.
How do rent-control laws differ across Canadian provinces?
Rent regulation varies considerably. Ontario generally limits annual increases for many covered rental units, but exemptions apply to some units first occupied for residential purposes after November 15, 2018. British Columbia sets annual allowable increases under provincial rules, while Alberta does not have a general cap on the amount of rent increases for periodic tenancies, though notice requirements apply. Tenants should check their province’s current legislation and any applicable exemptions before assuming a rent increase is lawful.
What measures are governments taking to improve rental affordability in Canada?
Governments use a combination of affordable-housing funding, rental assistance, social housing, construction financing, and infrastructure investment. Canada’s National Housing Strategy reported C$83.83 billion in funding commitments as of June 30, 2026, with 202,695 housing units created or committed and 366,869 community-housing units protected. The federal government is also using infrastructure funding and Build Canada Homes to support housing supply and affordability.
Mortgage & Rates
How are mortgage rates affecting Canada’s housing market?
Mortgage rates affect monthly payments, borrowing capacity, and the total cost of homeownership. Higher rates can reduce the number of buyers who qualify for a mortgage, while lower rates may improve affordability for some households. The effect also depends on home prices, down payments, income, and the mortgage products offered by lenders.
How do Bank of Canada interest rate decisions influence mortgage payments?
The Bank of Canada’s policy rate influences prime lending rates and the wider cost of borrowing, but it does not directly set every mortgage rate. Variable-rate mortgages are generally more sensitive to changes in prime rates, while fixed mortgage rates are influenced more by bond yields and lender pricing. The timing and size of any change to a borrower’s payment depend on their contract.
What is the difference between fixed-rate and variable-rate mortgages in Canada?
A fixed-rate mortgage keeps its interest rate unchanged for the agreed term, providing greater certainty about borrowing costs. A variable-rate mortgage has an interest rate that can move with the lender’s prime rate, although the way payments respond depends on the contract. Fixed rates offer predictability, while variable rates expose borrowers to interest-rate changes and potentially changing payments or repayment schedules.
How are mortgage costs affecting homeownership affordability?
Mortgage costs can determine whether a household can afford a particular property without sacrificing other essential expenses. Buyers must account for the interest rate, mortgage principal, property taxes, insurance, utilities, maintenance, and any condominium fees. Even when home prices decline, high borrowing costs can keep monthly payments expensive.
What is Canada’s mortgage stress test, and who must pass it?
The mortgage stress test checks whether borrowers could manage mortgage payments at a qualifying interest rate higher than their contract rate. For uninsured mortgages at federally regulated lenders, the Office of the Superintendent of Financial Institutions specifies the minimum qualifying rate as the greater of the contract rate plus 2 percentage points or 5.25%. The rules that apply can depend on the mortgage and lender, so borrowers should confirm their specific requirements.
hat should Canadian homeowners know before renewing their mortgages?
Homeowners should start reviewing renewal options several months before their current term ends. They should compare offers from their existing lender and other providers, review whether a fixed or variable rate suits their finances, and consider the costs of switching. Changes in income, outstanding debt, home value, and interest rates can affect the available options, so it is useful to plan for a range of payment scenarios.
How can borrowers compare mortgage offers from Canadian banks and lenders?
Borrowers should compare the interest rate, annual percentage cost where available, term, amortization, prepayment privileges, penalties, fees, and conditions for breaking or transferring the mortgage. A lower advertised rate is not always the least expensive option if it comes with restrictive terms or high penalties. Mortgage brokers and lenders can provide comparisons, but borrowers should read the complete offer before committing.
What factors should Canadians consider before choosing a mortgage?
Important factors include income stability, down-payment size, monthly affordability, tolerance for rate changes, expected time in the home, and future financial plans. Borrowers should understand whether payments can change, what happens at renewal, and whether they can make extra payments without penalties. The most suitable mortgage is one that fits both the household’s current budget and its ability to manage unexpected expenses.
New Developments
What major housing development projects are underway across Canada?
Canada has housing developments ranging from high-density apartment buildings and purpose-built rental projects to mixed-use neighbourhoods and affordable housing initiatives. Federal programs such as Build Canada Homes aim to support large-scale affordable housing, while infrastructure funding helps communities prepare for additional homes. Project locations, timelines, and the number of units delivered depend on local approvals, financing, and construction progress.
Which Canadian cities are seeing the most new home construction?
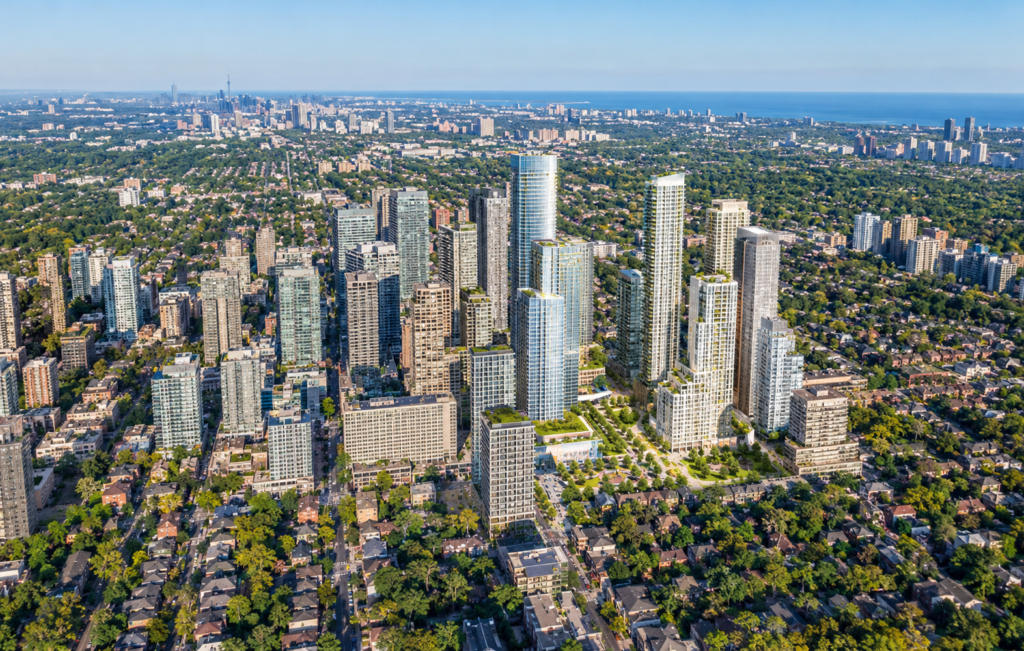
Construction activity changes from year to year, and the largest urban markets often account for substantial numbers of housing starts. Toronto, Montréal, Vancouver, Calgary, Edmonton, and Ottawa all have active residential development, but their project mix and construction rates differ. CMHC’s housing-starts reports provide the most useful comparisons because they distinguish monthly activity, annual trends, and units under construction.
How are new housing developments helping address Canada’s housing shortage?
New housing adds homes to the market and can expand options for buyers and renters. Purpose-built rental apartments, smaller homes, secondary suites, and higher-density developments can serve different household needs. However, new construction does not automatically make every neighbourhood affordable; the outcome depends on the number and type of homes delivered, location, rent or sale prices, and the availability of transportation and services.
What types of homes are being built to meet Canada’s changing housing needs?
Developments include detached houses, townhomes, duplexes, low-rise apartments, high-rise condominiums, purpose-built rentals, co-operative housing, and supportive housing. Modular and prefabricated construction can also help deliver some projects more efficiently when designs, approvals, and supply chains are well coordinated. A varied housing supply is important because families, students, seniors, newcomers, and people with disabilities have different needs.
How are condominium and purpose-built rental developments changing Canadian cities?
Condominium projects provide homes that can be purchased by owner-occupiers or investors, while purpose-built rental buildings are designed specifically for long-term renting. New developments can increase density near jobs, schools, and transit, potentially supporting more compact communities. The benefits depend on construction costs, the pace of delivery, building quality, maintenance, and whether the units meet local affordability needs.
What role does infrastructure play in the success of new housing communities?
Housing requires reliable water and wastewater systems, roads, public transit, electricity, schools, healthcare access, and other community services. Without sufficient infrastructure, even approved housing projects may face delays or place pressure on existing services. The federal Canada Housing Infrastructure Fund supports water, wastewater, stormwater, and solid-waste infrastructure that can enable additional housing.
How are construction costs and labour shortages affecting housing development in Canada?
Higher costs for materials, land, financing, insurance, and labour can make residential projects more expensive and reduce their financial viability. A shortage of skilled tradespeople can delay schedules and limit how quickly developers complete projects. Builders may respond through standardized designs, modern construction methods, improved project planning, and partnerships that help manage costs and reduce delays.
What challenges are delaying new residential construction across Canada?
Common challenges include zoning and approval processes, financing conditions, infrastructure constraints, labour availability, material costs, and complex project requirements. Some developments also face weak pre-construction sales or rents that do not support projected building costs. Improving coordination between governments, utilities, lenders, and builders can help, but projects still need to meet safety, environmental, and planning standards.
Affordable Housing Policy
What are the latest federal policies aimed at improving housing affordability in Canada?
Federal priorities include increasing housing supply, supporting affordable and community housing, investing in infrastructure, and addressing homelessness. Build Canada Homes, launched in September 2025, is intended to finance and support large-scale affordable housing development. The federal government is also investing through the Canada Housing Infrastructure Fund and the Build Communities Strong Fund to help communities provide the infrastructure needed for housing growth.
Which federal housing programs support affordable homeownership and rental housing?
Programs and initiatives include the First Home Savings Account, the Home Buyers’ Plan, the National Housing Strategy, the Apartment Construction Loan Program, and the Co-operative Housing Development Program. Different initiatives serve different purposes: some help eligible individuals save for a home, while others support housing providers and developers. Eligibility, application windows, and funding availability must be checked through official program pages.
How are provincial and municipal governments addressing housing affordability?
Provincial and municipal governments use zoning changes, faster permitting, rental regulations, affordable-housing investments, development incentives, and local infrastructure planning. Some jurisdictions encourage secondary suites and higher-density construction near transit, while others provide rent supplements or support non-profit housing providers. Results depend on local market conditions, funding, implementation, and coordination across levels of government.
What financial assistance is available to eligible low-income renters in Canada?
Depending on their location and circumstances, eligible renters may qualify for provincial or territorial rent supplements, social housing, housing benefits, or municipal assistance. Some programs prioritize seniors, people with disabilities, families with children, or individuals facing housing insecurity. Eligibility, payment amounts, and wait times vary, so renters should consult their local housing authority and government benefits services.
How are governments addressing homelessness and the need for supportive housing?
Governments fund emergency shelters, transitional housing, permanent supportive housing, outreach, and programs designed to prevent people from losing their homes. Supportive housing combines accommodation with services that may include mental health care, substance-use support, and assistance with daily living. Long-term progress depends on adequate housing supply, stable funding, and coordinated support that addresses the reasons people experience homelessness.
What role does social housing play in Canada’s affordable housing system?
Social housing provides accommodation at below-market rents or through other affordability arrangements for eligible households. It can support people whose incomes make private-market housing difficult to afford, including families, seniors, and people with disabilities. Maintaining existing buildings and constructing new units are both important because demand can exceed available supply and older properties may need substantial repairs.
How are housing policies affecting developers, landlords, renters and homebuyers?
Housing policies can change the cost and feasibility of building homes, the rules for rent increases, access to financial support, and the conditions under which properties may be used. Developers may benefit from infrastructure or financing programs but must meet program requirements. Renters and buyers may gain protection or assistance, although the practical effect depends on eligibility, local market conditions, and how policies are implemented.
What challenges must Canada overcome to increase the supply of affordable housing?
Canada needs more housing that households can actually afford, not just a larger number of homes at any price. Key challenges include construction costs, infrastructure capacity, planning delays, limited skilled labour, financing, and the need to preserve existing affordable units. Strong coordination between governments, Indigenous communities, non-profit providers, and private builders can help expand supply and make better use of public investment.
Airbnb & Short-Term Rentals
What are the rules for operating Airbnb and other short-term rentals in Canada?
There is no single national rule covering every short-term rental. Municipalities set local requirements for zoning, principal residences, registration, licences, and permitted rental periods, while provinces may impose additional rules and taxes. Hosts should also check lease agreements, condominium bylaws, insurance conditions, and income-tax obligations before listing a property.
How do short-term rental regulations differ across Canadian cities?
Rules can differ substantially between cities. Toronto generally limits short-term rentals to a host’s principal residence and distinguishes between renting rooms and the entire home. Vancouver requires a short-term rental business licence for stays of fewer than 90 consecutive days and also requires the property to be the host’s principal residence. Other municipalities may apply different definitions, licensing conditions, or restrictions.
What are Toronto’s rules for Airbnb and other short-term rental properties?
Toronto defines a short-term rental as all or part of a dwelling rented for fewer than 28 consecutive days. Hosts must register with the city and use their principal residence. They may rent up to three bedrooms for an unlimited number of nights per year, or rent the entire home for a maximum of 180 nights per calendar year. Hosts must also comply with applicable building, fire, and condominium rules.
What restrictions and registration requirements apply to short-term rentals in Vancouver?
Vancouver requires a business licence for short-term rentals of fewer than 90 consecutive days. The property must be the host’s principal residence, and a host must meet the city’s ownership or tenancy requirements. Landlord and strata approval are required where applicable, and the licence number must appear in online listings. The city lists a C1,108licencefeeandaC77 application fee, so hosts should verify the current fees before applying.
How are short-term rentals affecting the supply of long-term rental housing in Canada?
In areas with strong tourism demand, converting entire homes or apartments into short-term accommodation can reduce the number available for long-term tenants. The scale of the effect varies by city, neighbourhood, and type of property. Short-term rentals can also provide income for residents and accommodation for visitors, so governments often try to balance these benefits against the need to preserve long-term housing.
What licences, registrations and taxes may short-term rental hosts need to comply with?
Hosts may need a municipal licence or registration, permission under local zoning rules, and approval under a lease or condominium bylaws. Depending on the jurisdiction and transaction, taxes may include income tax, GST/HST, provincial sales taxes, or municipal accommodation taxes. Requirements differ, so hosts should check municipal rules and Canada Revenue Agency guidance and keep accurate records of rental income and expenses.
How are Canadian governments enforcing short-term rental regulations?
Enforcement can include registration checks, licence-number verification, online listing reviews, complaints, inspections, penalties, and requirements for platforms to share or verify certain information. Toronto and Vancouver have city-specific compliance systems and consequences for operating outside their rules. Hosts should retain proof of registration, ensure listings are accurate, and confirm that the property meets all applicable requirements.
What should property owners know before investing in an Airbnb or short-term rental business in Canada?
Investors should confirm that the property is legally eligible for short-term rentals before buying it. They should calculate realistic revenue after cleaning, maintenance, utilities, insurance, platform fees, taxes, vacancy, and licensing costs. They must also review mortgage conditions, zoning rules, condominium restrictions, and the possibility that local regulations may change. A property that works as a long-term rental may not legally qualify for short-term rental use.
Final Verdict
Canada’s housing and real estate market in 2026 presents different challenges for buyers, renters, homeowners, developers, and investors. Home sales have weakened in several markets, rental asking prices have eased in some cities, and housing affordability remains a concern for many households. Meanwhile, construction costs, mortgage qualification requirements, and regional differences continue to influence access to housing.
Government programs such as the FHSA, Home Buyers’ Plan, National Housing Strategy, and housing infrastructure funds can help eligible Canadians or support new housing development. However, lasting improvements will require more homes at a range of price points, reliable infrastructure, efficient approvals, and continued investment in affordable and supportive housing.
For property owners considering Airbnb, understanding municipal regulations is just as important as estimating rental income. Canada’s long-term housing challenge is not simply to build more homes, but to ensure that suitable, safe, and affordable housing is available in the communities where people need it
Table of Contents
Leave a Reply