Canada Housing & Real Estate
Introduction
Canada’s housing market remains divided across regions as October 2026 begins. National home prices are below their level a year earlier, while sales activity remains relatively soft and buyers have more inventory than during the pandemic-era boom. CREA reported that the national MLS® Home Price Index was down 3% year over year in August, while national inventory remained around 4.8 months.
The rental market has also changed considerably. Average asking rent reached about $2,035 in August, down 4.8% from a year earlier, with increased rental supply helping conditions in several major cities. However, lower-cost rental units remain difficult to find.
Construction is another important part of the story. CMHC says Canada needs roughly 417,000–469,000 housing starts annually to restore affordability to pre-pandemic levels by 2036. Calgary and Edmonton are performing relatively strongly on supply, while Toronto, Vancouver and Montreal continue to face different combinations of affordability, construction and supply challenges.
For buyers, first-time homeowners, renters, investors and landlords, the Canadian housing market therefore looks very different depending on the city, property type and financial situation.
Market Updates
What is the current situation of Canada’s housing market in October 2026?
Canada’s housing market is relatively balanced compared with the extreme conditions seen during the pandemic. The national MLS Home Price Index was about 3% lower year over year in August 2026, while prices were largely stable from one month to the next.
National inventory remained around 4.8 months, close to the long-term average. Sales have also remained below last year’s levels.
The market is therefore not experiencing a broad national boom. Instead, buyers generally have more choice and negotiating power, although conditions vary considerably between provinces and cities.
What are the recent changes in Canadian home prices?
Canadian home prices have moved in different directions depending on location. The national benchmark price declined about 3% year over year in August 2026.
Ontario and British Columbia remained among the softer markets, while Quebec and several Prairie and Atlantic markets recorded stronger annual price performance.
Greater Toronto’s MLS HPI benchmark was down about 4.5% year over year, while Greater Vancouver’s benchmark was down about 6%.
By comparison, Montreal continued to show positive annual price growth, demonstrating that Canada’s housing market cannot be described using a single national trend.
What is the current trend in home sales and housing inventory in Canada?
Home sales remain relatively subdued. August 2026 national sales were below the level recorded a year earlier, while inventory remained close to five months of supply.
CREA reported nearly 200,000 properties listed for sale nationally at the end of August, around 1.4% above the previous year.
The 4.8-month inventory level is below the long-term five-month average but well above the level normally associated with a strong seller’s market.
This gives many buyers more time to compare properties and negotiate than they had during the tightest periods of the housing boom.
How are Toronto, Vancouver, Calgary, Edmonton and Montreal housing markets different?
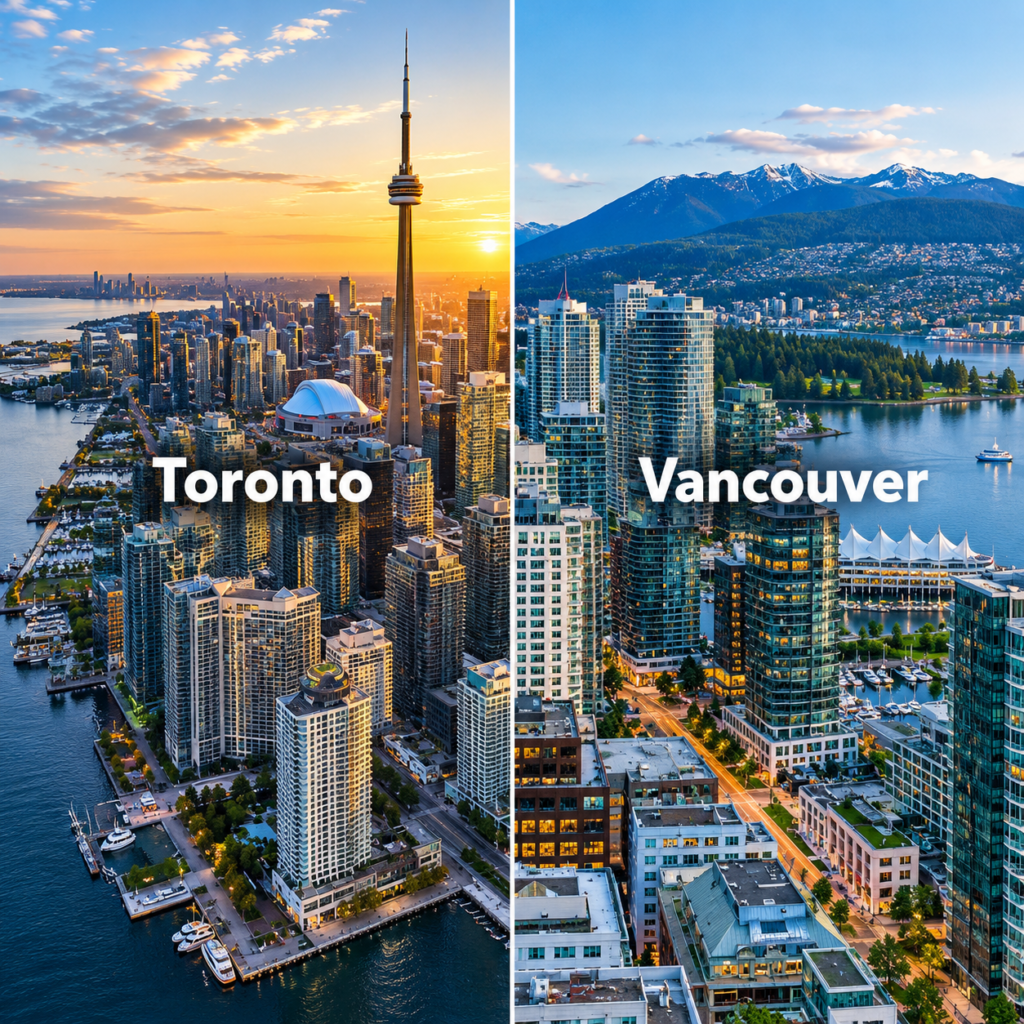
Toronto and Vancouver remain expensive but have experienced significant price pressure and weaker demand. Toronto’s benchmark price was down about 4.5% year over year in August, while Greater Vancouver’s was down about 6%.
Calgary and Edmonton remain relatively more affordable and have benefited from stronger construction activity. CMHC says Calgary has substantially reduced its housing supply gap, while Edmonton has no measurable housing supply gap among the major markets.
Montreal is different again, with prices showing annual growth despite some monthly cooling.
How affordable is Canada’s housing market for buyers?
Housing affordability has improved somewhat from the peak of the affordability crisis, mainly because prices have softened in several expensive markets and borrowing costs are lower than their previous highs.
However, affordability remains a major challenge in Toronto and Vancouver because home prices are still very high relative to household incomes.
CMHC warns that recent affordability improvements could be temporary if housing construction slows.
The long-term challenge is therefore not simply lower prices but increasing the supply of homes that households can realistically afford.
What developments are occurring in new construction and resale homes?
Canada’s resale market has remained relatively soft while new construction has increasingly shifted toward rental housing.
CMHC’s 2026 Housing Supply Report highlights strong rental construction but weaker ownership-oriented construction, particularly condominium development.
August 2026 housing-start trends remained elevated but declined about 1.3% from July on a six-month trend basis.
Montreal and Vancouver recorded increases in their six-month construction trends, while Toronto’s trend was flat.
What factors are affecting housing demand and supply?
Interest rates, household income, employment, population growth, immigration, construction costs, land availability and government policy are all influencing Canada’s housing market.
Mortgage affordability remains particularly important because even modest changes in borrowing costs can affect purchasing power.
Construction costs and financing conditions also influence whether developers start new projects.
At the same time, population changes affect demand for both ownership and rental housing.
8. What are the major Canadian housing-market trends in October 2026?
The major trends include softer national home prices, relatively subdued resale activity, more balanced inventory, easing rents and a shift toward rental construction.
Toronto and Vancouver remain under greater price pressure than Calgary and Edmonton.
Rental supply has improved conditions in several markets, but affordable rental units remain difficult to secure.
The biggest long-term concern is that weaker ownership construction could eventually limit supply and reverse some of the recent affordability improvements.
First-Time Buyers
What are the important updates for first-time home buyers in Canada?
First-time buyers continue to have access to several federal programs designed to reduce the cost of entering the housing market.
The First Home Savings Account allows eligible buyers to save with tax advantages, while the Home Buyers’ Plan allows qualifying buyers to withdraw money from an RRSP.
The federal First-Time Home Buyers’ GST/HST rebate is also an important 2026 measure for eligible purchases of new homes.
Buyers should still consider mortgage qualification, closing costs, property taxes, insurance and maintenance before determining what they can afford.
What are the basic requirements for buying a first home in Canada?
A first-time buyer generally needs sufficient income, acceptable credit, funds for the down payment and the ability to qualify for a mortgage.
Lenders examine income, existing debts, credit history, down payment and housing costs.
The buyer also needs to budget for closing costs such as legal fees, land-transfer taxes where applicable, inspections and adjustments.
Eligibility for specific first-time-buyer programs can have additional conditions, so buyers should check the rules before making a purchase.
What are the minimum down payment rules for first-time buyers?
For homes priced at $500,000 or less, the minimum down payment is generally 5%.
For homes above $500,000 but below $1.5 million, buyers generally need 5% on the first $500,000 and 10% on the portion above $500,000.
For homes priced at $1.5 million or more, the minimum down payment is generally 20%.
A down payment below 20% will normally require mortgage loan insurance.
How does the First Home Savings Account work?
The First Home Savings Account, or FHSA, is designed to help eligible Canadians save for their first home.
The annual contribution limit is generally $8,000, while the lifetime contribution limit is $40,000.
Eligible contributions can provide a tax deduction, while qualifying withdrawals for a first home are tax-free.
Unused room can generally be carried forward, subject to FHSA rules and limits.
How does the Home Buyers’ Plan help first-time buyers?
The Home Buyers’ Plan allows eligible individuals to withdraw up to $60,000 from their RRSP to buy or build a qualifying home.
The withdrawal can be made without immediate income tax if the program’s conditions are met.
Amounts withdrawn under the HBP generally have to be repaid to the RRSP over a period of up to 15 years.
For couples who both qualify, each person may potentially use their own HBP limit.
What government incentives and rebates are available to first-time buyers?
The federal First-Time Home Buyers’ GST/HST rebate is one of the major current incentives.
Eligible buyers purchasing qualifying new homes priced at or below $1 million can receive up to $50,000, while the rebate is gradually reduced for homes priced between $1 million and $1.5 million.
There is no rebate under this federal program for qualifying homes priced at or above $1.5 million.
Provincial and municipal programs may provide additional assistance depending on where the buyer lives.
What mortgage qualification requirements do first-time buyers need to meet?
Mortgage lenders generally assess income, employment, credit history, existing debts and the size of the down payment.
The lender also evaluates whether the borrower can afford mortgage payments alongside property taxes, heating costs and other obligations.
For uninsured mortgages, OSFI’s minimum qualifying rate remains the greater of the mortgage contract rate plus 2 percentage points or 5.25%.
Getting mortgage pre-approval can help buyers understand their realistic price range before making an offer.
What additional costs should first-time buyers consider?
The purchase price is only one part of the total cost of buying a home.
Buyers should budget for legal fees, home inspection costs, appraisal fees, land-transfer taxes where applicable, title insurance and moving expenses.
There may also be mortgage insurance costs when the down payment is below 20%.
After closing, homeowners need to account for property taxes, utilities, insurance, maintenance and unexpected repairs.
Rental Crisis
What is the current situation of Canada’s rental market in October 2026?
Canada’s rental market has become less expensive in many areas compared with the previous year, although affordability remains a serious issue.
The September 2026 Rentals.ca report showed an average Canadian asking rent of approximately $2,035 in August, down 4.8% year over year.
This represented the 23rd consecutive month of annual rent declines.
However, lower rents do not mean that all renters have easy access to affordable housing because lower-priced units remain much more competitive.
What is the current trend in average Canadian rents?
Average asking rents have been trending lower nationally.
In August 2026, average asking rent was approximately $2,035, down 4.8% from the previous year.
Purpose-built rental units were comparatively resilient, while condo rents and secondary-market units experienced larger declines.
The improvement has been connected to increased rental supply, softer population growth and changes in rental demand.
How do rental costs differ between Toronto, Vancouver, Calgary, Edmonton and Montreal?
Vancouver remains one of Canada’s most expensive rental markets, with average apartment and condo asking rent around $2,704 in August 2026.
Toronto followed at approximately $2,570.
Calgary was around $1,825, Montreal about $1,955 and Edmonton approximately $1,520.
The gap demonstrates the major affordability differences between Canadian cities, with Edmonton remaining considerably cheaper than Vancouver and Toronto.
What are the major causes of Canada’s rental housing shortage?
The rental shortage has been driven by years of insufficient housing construction, strong population growth, high land costs and limited availability of affordable units.
Construction of purpose-built rentals has increased significantly, helping to improve vacancy conditions.
However, new rental projects often target higher-income households because construction and financing costs are high.
This means that vacancy can improve while lower-income renters still struggle to find affordable homes.
How are rental supply and demand affecting Canadian tenants?
Increasing rental supply is giving tenants more choice in several Canadian cities.
The national purpose-built rental vacancy rate reached 3.1% in 2025, up from 2.2% the previous year.
As more new units enter the market, landlords in some areas are offering incentives or reducing asking rents to attract tenants.
However, the benefits are not evenly distributed, and lower-priced rental units remain much more competitive.
What is the current situation of affordable rental housing?
Affordable rental housing remains one of Canada’s biggest housing challenges.
New construction has improved supply, but many new apartments are priced above what low- and moderate-income households can comfortably afford.
Government-supported affordable housing and non-market housing therefore remain important.
The gap between market rents and household incomes is particularly difficult for people receiving low incomes, newcomers and households with unstable employment.
How do rent-control rules differ among Canadian provinces?
Rent-control systems are primarily provincial, and the rules vary considerably.
Ontario generally limits annual rent increases for many covered units, while some newer units have different rules.
British Columbia also regulates allowable annual increases for covered rental units.
Quebec uses its own rent-setting framework, while Alberta does not have the same province-wide rent-control structure.
Renters should therefore check the rules in their specific province and understand whether their unit is covered.
What challenges do newcomers and low-income households face in Canada’s rental market?
Newcomers may face challenges such as limited Canadian credit history, employment verification requirements and difficulty providing a rental history.
Low-income households face an additional problem because affordable units are often in the shortest supply.
Competition can therefore be much stronger at the lower end of the rental market.
Government housing programs, community organizations and non-profit housing providers can play an important role in helping vulnerable renters.
Mortgage & Rates
What is the current mortgage-rate trend in Canada in October 2026?
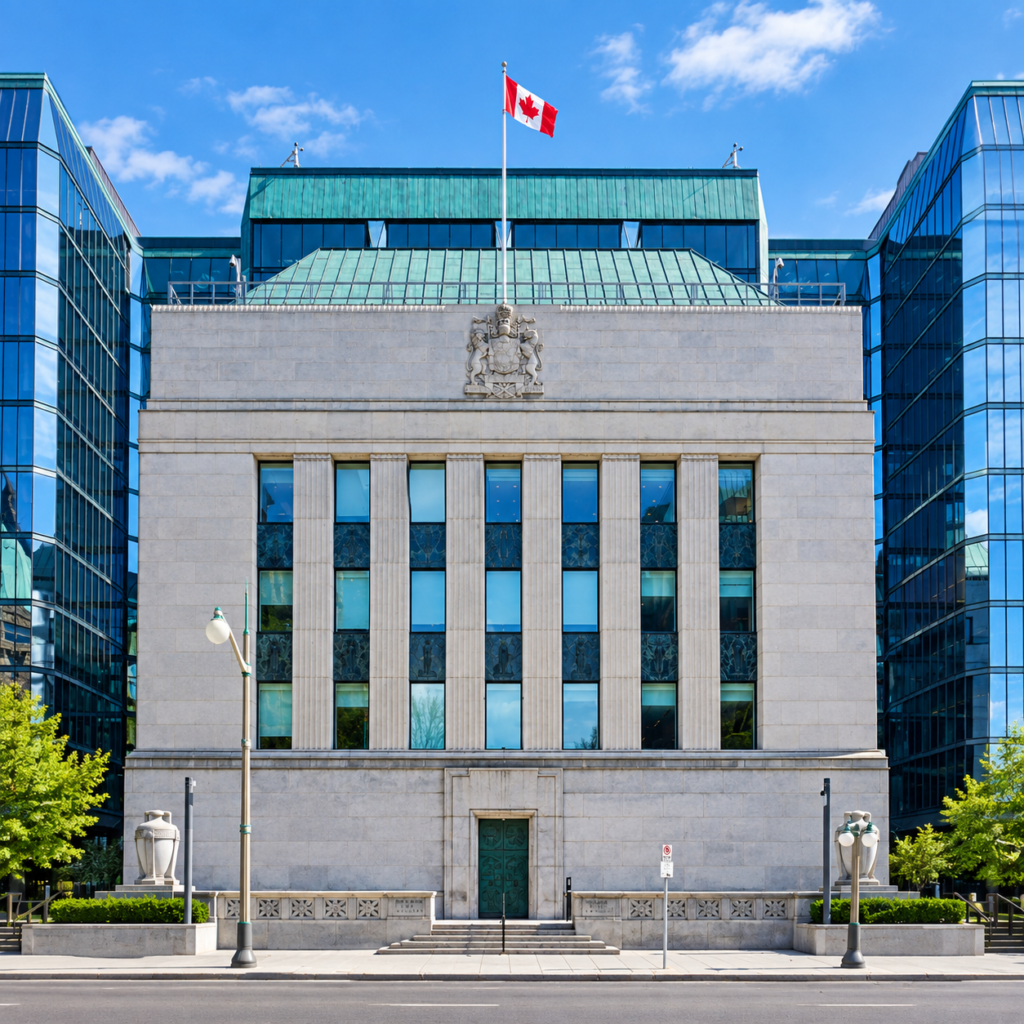
Mortgage rates remain sensitive to both Bank of Canada policy and bond-market conditions.
The Bank of Canada held its overnight policy rate at 2.25% on September 2, 2026, and the rate remained at 2.25% entering October.
Variable mortgage rates are more directly influenced by changes in the policy rate.
Fixed mortgage rates are influenced more heavily by bond yields and lenders’ funding costs.
How do Bank of Canada interest-rate changes affect mortgages?
When the Bank of Canada raises or lowers its policy rate, lenders can adjust their prime rates.
This has a direct effect on many variable-rate and adjustable-rate mortgages.
Fixed mortgage rates are not mechanically tied to the overnight rate and can move based on bond-market expectations.
Therefore, a Bank of Canada rate decision can influence mortgages differently depending on the mortgage type.
What is the difference between fixed-rate and variable-rate mortgages?
A fixed-rate mortgage keeps the interest rate unchanged for the agreed term.
This gives borrowers greater payment certainty and protection from short-term rate increases.
A variable-rate mortgage can change as the lender’s prime rate changes.
Variable mortgages can become cheaper when rates fall but can also become more expensive when interest rates rise.
How does mortgage qualification work for Canadian home buyers?
Mortgage qualification considers income, debt obligations, credit history, down payment and the property’s value.
Lenders calculate whether the borrower can handle the proposed mortgage payment along with other housing expenses.
The mortgage stress test provides an additional affordability assessment for applicable borrowers.
Getting pre-approved can help buyers understand how much they may be able to borrow before shopping for a property.
What is the mortgage stress test and who is subject to it?
The mortgage stress test is designed to ensure borrowers can continue making payments if interest rates rise.
For uninsured mortgages, OSFI’s minimum qualifying rate is currently the greater of the contract mortgage rate plus 2 percentage points or 5.25%.
The test is particularly important when determining how much a borrower can qualify for.
Borrowers should therefore avoid using their maximum approved amount as automatically being a comfortable household budget.
How are mortgage renewals affecting Canadian homeowners?
Homeowners renewing mortgages may face a different interest rate from the rate they received several years earlier.
Even if market rates have declined from previous peaks, some borrowers may still see payment changes depending on when their existing mortgage was arranged.
Renewal can therefore affect household cash flow and spending.
Homeowners approaching renewal should compare lenders, terms, amortization options and total borrowing costs rather than focusing only on the advertised interest rate.
How do higher or lower interest rates change home affordability?
Lower interest rates generally increase borrowing capacity because monthly mortgage payments can become smaller.
Higher rates have the opposite effect and can reduce the amount a household can qualify for.
However, lower rates can also increase demand if more buyers enter the market, potentially putting upward pressure on prices.
Affordability therefore depends on the combination of home prices, mortgage rates, household income and available housing supply.
What costs should first-time buyers focus on when choosing a mortgage?
Buyers should look beyond the headline interest rate.
Important costs include the mortgage payment, lender fees, mortgage insurance, appraisal costs, penalties for breaking the mortgage and the cost of refinancing or renewing.
The mortgage term and amortization period also affect total interest paid.
A slightly higher rate may sometimes offer greater flexibility, while a lower rate may have stricter conditions.
New Developments
What major housing developments are underway in Canada?
Canada continues to support large-scale housing and infrastructure investment designed to increase housing supply.
Federal programs are targeting infrastructure such as water systems, transit and roads that can unlock additional housing construction.
The Build Communities Strong Fund provides $51 billion over 10 years starting in 2026–27, with housing-related infrastructure among its priorities.
However, the number of homes actually delivered will depend on provincial, municipal and private-sector construction activity.
What is the status of new housing projects in Toronto, Vancouver, Calgary and other cities?
Construction conditions differ significantly.
Calgary has recorded particularly strong housing construction and has substantially reduced its housing supply gap.
Edmonton has kept construction broadly in line with population growth and has no measurable housing supply gap according to CMHC.
Toronto and Vancouver continue to face challenges from high development costs, weaker ownership demand and slower condominium construction.
What is the current situation of new-home construction in Canada?
New construction remains elevated compared with many previous years but is showing signs of moderation.
CMHC reported that the six-month trend in housing starts declined 1.3% in August to approximately 244,149 units.
The standalone seasonally adjusted annual rate was about 229,046 units in August.
CMHC expects construction activity to moderate, particularly toward the end of 2026.
What are the trends in condos and purpose-built rental developments?
The market is increasingly shifting toward purpose-built rental construction.
CMHC reports that rental construction has been a major driver of housing supply in several large Canadian markets.
At the same time, condominium construction is facing greater challenges because of weaker presales and affordability pressures.
This creates a potential long-term problem because condos have traditionally provided a significant source of ownership housing.
What are Canadian governments doing to increase housing supply?
Governments are using several approaches, including infrastructure investment, housing incentives, financing programs and measures designed to accelerate development.
The Canada Housing Infrastructure Fund supports infrastructure needed to enable housing construction.
The Build Communities Strong Fund is also designed to support infrastructure such as water, transportation and community systems.
Municipal zoning and development reforms are another important part of increasing housing capacity.
What role do affordable units play in new housing projects?
Affordable units help ensure that new housing supply benefits households across different income levels.
Without affordable and non-market housing, much of the new construction may remain unaffordable to lower-income households.
Federal, provincial and municipal programs can provide financing or incentives for affordable and supportive housing.
The challenge is to balance affordability with the high cost of land, labour, materials and financing.
How does infrastructure development affect new housing projects?
Housing cannot be built efficiently without adequate infrastructure.
Roads, public transit, water, wastewater, electricity and other services can determine whether new communities are practical to develop.
The Canada Housing Infrastructure Fund specifically supports infrastructure needed to enable housing growth.
Infrastructure investment can therefore increase the number of homes that municipalities can accommodate over time.
What are the current housing-construction challenges in Canada’s major urban centres?
Major challenges include high construction costs, financing costs, land prices, development approvals and weaker demand for some ownership projects.
Toronto and Vancouver face particularly high land and construction costs.
Condominium presales have weakened in several markets, making it harder for developers to finance new ownership projects.
CMHC warns that if construction slows too much, today’s affordability improvements may not last.
Affordable Housing Policy
What are the major developments in Canada’s affordable housing policies?
Canada’s housing strategy increasingly combines direct housing investment with infrastructure funding.
The federal government is supporting programs intended to increase housing supply, improve affordability and unlock development.
Recent policy measures also include incentives for first-time buyers and infrastructure programs.
The main challenge is ensuring that increased construction produces housing that is affordable to a broad range of households.
What federal programs support affordable housing in Canada?
Federal housing support includes infrastructure programs, housing benefits, financing initiatives and programs delivered with provinces, territories, municipalities and housing organizations.
The Canada Housing Infrastructure Fund supports infrastructure required for housing.
The federal government also continues to support housing-related investments through various programs and agreements.
Different programs target different needs, from market housing supply to affordable and supportive housing.
What is the Canada Housing Infrastructure Fund and what role does it play?
The Canada Housing Infrastructure Fund, or CHIF, helps provinces and territories finance infrastructure required to support housing.
Its focus includes essential services such as drinking water and wastewater infrastructure.
These systems can be a major limitation on new housing development.
By supporting infrastructure, the program aims to help communities accommodate additional homes and reduce some of the costs associated with expansion.
How are provinces and municipalities increasing affordable housing supply?
Provinces and municipalities use a mixture of zoning reforms, development incentives, funding programs, land strategies and partnerships with non-profit housing providers.
Some municipalities are also trying to speed up approvals and increase density around transit and established neighbourhoods.
The exact approach differs by province and city.
Successful housing policy therefore depends on cooperation among federal, provincial and municipal governments.
How does government funding for affordable housing work?
Government housing funding can be provided through grants, loans, financing agreements, tax measures or infrastructure investments.
Programs may target construction, renovation, supportive housing or infrastructure.
Public funding can reduce the financial risk of projects that would otherwise be difficult to build at affordable rents.
In many cases, governments work with municipalities, provinces, non-profits and private developers to deliver projects.
What is the difference between social housing and affordable housing?
Social housing generally refers to housing supported through government or non-profit arrangements where rents are often tied to household income or provided below market rates.
Affordable housing is a broader term and can include housing priced below market rates but not necessarily based directly on a household’s income.
Some affordable housing is privately operated, while social housing is commonly associated with public or non-profit providers.
The two terms therefore overlap but are not identical.
What measures are being used to address homelessness and housing affordability?
Canada’s response includes supportive housing, homelessness programs, affordable housing investments and measures designed to increase overall housing supply.
Homelessness policy also requires services beyond simply constructing homes, including mental-health, employment and community supports.
Increasing affordable rental supply can help reduce the number of households at risk of homelessness.
Long-term results depend on both housing construction and the availability of supportive services.
What impact do affordable housing policies have on renters and low-income households?
Effective affordable housing programs can reduce housing costs and provide greater stability for households with limited incomes.
New affordable and supportive housing can also reduce pressure on the private rental market.
However, demand remains much greater than the supply of deeply affordable units in many communities.
As a result, government policy can improve conditions without completely eliminating affordability challenges.
Airbnb & Short-Term Rentals
What are Canada’s Airbnb and short-term rental rules in October 2026?
There is no single national short-term-rental rule covering every Canadian city.
Municipalities and provinces establish their own licensing, zoning, registration and operating requirements.
Toronto, Vancouver and Quebec have particularly detailed frameworks.
Hosts should therefore verify both municipal and provincial requirements before listing a property on Airbnb or another platform.
How do short-term rental regulations differ between Canadian cities?
Rules can differ significantly.
Toronto generally restricts short-term rentals to a host’s principal residence and limits entire-home rentals to 180 nights per year.
Vancouver requires the property to be the operator’s principal residence and requires a city short-term rental licence.
Quebec requires registration for tourist accommodation offered for stays of 31 days or less and also requires compliance with municipal rules.
What are the short-term rental rules in Toronto?
Toronto defines a short-term rental as accommodation rented for less than 28 consecutive days.
Hosts generally must operate from their principal residence and register with the City.
An entire home can generally be rented for a maximum of 180 nights per calendar year.
Hosts can rent up to three bedrooms in their principal residence under the applicable partial-unit rules.
What are the short-term rental rules in Vancouver?
Vancouver requires a short-term rental business licence for rentals of less than 90 consecutive days.
The property must be the operator’s principal residence.
The current city licence fee is $1,108 annually, plus a $77 application fee.
Hosts must display their licence number in online listings and also comply with applicable provincial registration requirements.
How do short-term rentals affect Canada’s long-term rental supply?
Short-term rentals can potentially reduce the number of homes available for long-term tenants when entire housing units are frequently used for tourism.
This is one reason municipalities such as Toronto and Vancouver restrict short-term rentals to principal residences.
The impact varies by neighbourhood and city.
Regulators generally aim to balance tourism and additional income for residents with the need to preserve long-term rental housing.
What tax requirements apply to Canadian Airbnb hosts?
Income earned from short-term rentals generally needs to be reported for tax purposes.
Hosts may be able to deduct eligible expenses related to earning rental income.
However, since 2024, expenses related to non-compliant short-term rentals can be restricted under federal tax rules.
Hosts should therefore make sure their rental complies with applicable municipal and provincial licensing and registration requirements.
How do short-term rental licences and registration requirements work?
Requirements depend on the jurisdiction.
Toronto requires municipal registration for eligible short-term rental operators.
Vancouver requires a city business licence and provincial registration.
Quebec requires tourist-accommodation registration for qualifying stays of 31 days or less and requires municipal compliance documentation.
Hosts should also check zoning, insurance, strata or landlord rules before operating.
Why do Canadian municipalities regulate short-term rentals?
Municipalities regulate short-term rentals for several reasons.
One major goal is to protect long-term rental housing by preventing large numbers of residential units from being converted entirely to tourist accommodation.
Rules also address safety, zoning, neighbourhood disturbances, taxation and consumer protection.
Toronto and Vancouver explicitly link their short-term-rental frameworks to protecting housing supply and ensuring compliant operation.
Final Verdict
Canada’s housing market in October 2026 is best described as regional rather than national. Home prices and sales remain under pressure in expensive markets such as Toronto and Vancouver, while Calgary and Edmonton continue to benefit from stronger housing construction and comparatively better affordability.
The rental market has improved from the extreme conditions of previous years, with national asking rents down 4.8% year over year in August. Nevertheless, affordable rentals remain difficult to secure, particularly for lower-income households.
Mortgage conditions are also more stable than during the earlier rate-hike cycle, with the Bank of Canada’s policy rate at 2.25% entering October. Even so, mortgage qualification and affordability remain major barriers for many buyers.
The biggest long-term issue is housing supply. Canada needs substantially more annual housing starts to restore pre-pandemic affordability, and weaker ownership-oriented construction could create new supply problems in the future.
For first-time buyers, programs such as the FHSA, Home Buyers’ Plan and new GST/HST rebate can reduce some of the financial burden. For renters and landlords, however, affordability and local regulations remain highly dependent on the city and province.
Overall, Canada’s housing market is becoming more balanced, but balanced does not necessarily mean affordable. The next phase of Canada’s housing story will depend heavily on construction, interest rates, household incomes, population trends and government housing policy.
Table of Contents
Leave a Reply